Africa doesn’t have a housing problem. It has a financing problem!
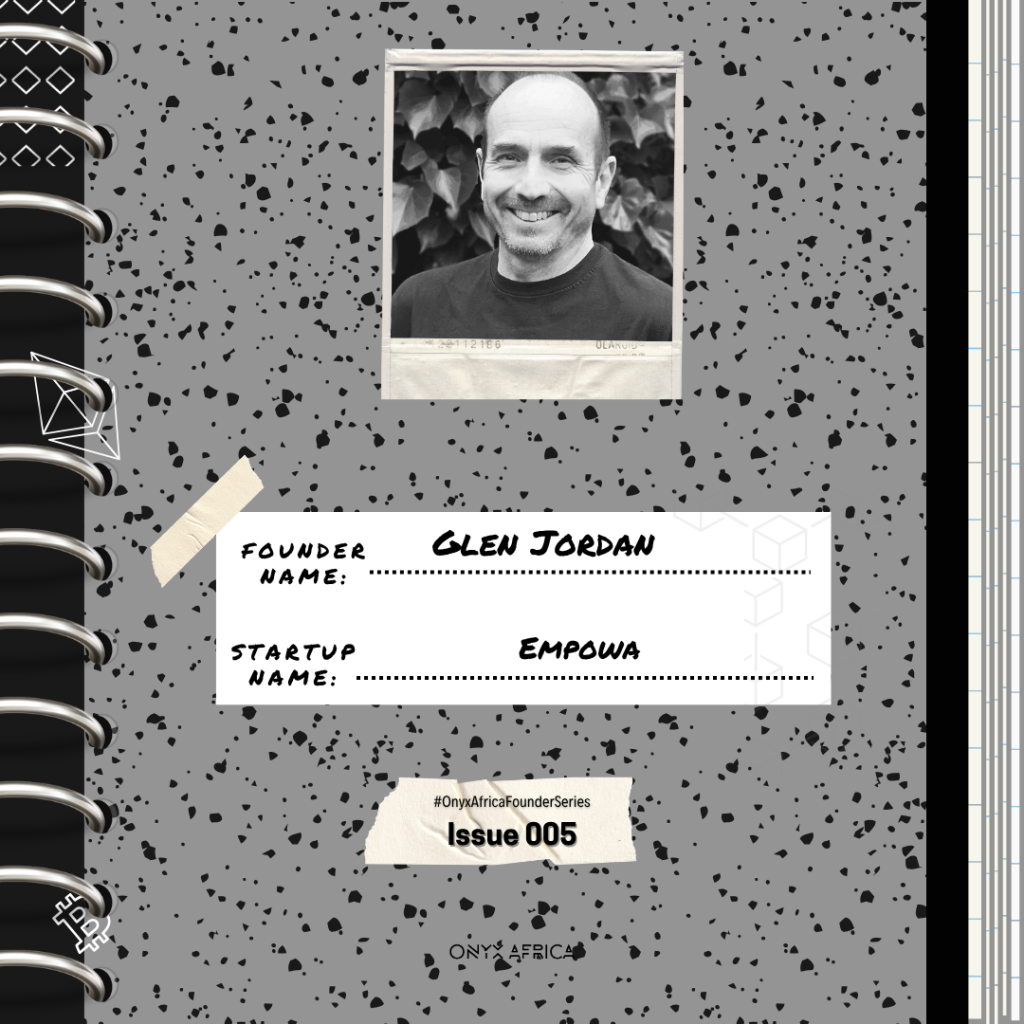
Glen Jordan saw it firsthand — families in Cape Town’s informal settlements were paying more per square meter than those in the suburbs.
That disconnect sparked Empowa: a platform using blockchain and Modern Methods of Construction to deliver affordable, climate-resilient housing to Africa’s unbanked.
Forget theory. Empowa is backing real developments — and using Web3 to replace broken systems with something better…
Glen, Let’s take it back — everyone’s got that first “aha” moment that flips the switch. What was your first encounter with the Web3 rabbit hole — and what made you stay? Was it Bitcoin? Smart contracts? A tweet that just hit different? Walk us through the moment you realized Web3 wasn’t just tech — it was something that could change the game, especially on the continent…What was that spark for you that led to creating Empowa?
Yeah, it’s actually, it’s interesting. It was far more practical than that. Actually, ironically. How I got into the space was – I was living in Hout Bay, and in Hout Bay, there is an informal settlement called Imizamo Yethu, and while I was looking into it – I was actually doing some research into pensions for people who weren’t formally employed, how to create pensions, I discovered, to my horror, and I’m embarrassed to say this, as a white South African, I discovered, to my horror, that people in Imizamo Yethu were paying between four and seven times more per square meter to rent the land on which they built their shack, then people were paying in the center of Cape Town for an apartment.
When I realized that, was when I suddenly realized that the housing issue is not a function of poverty, because the assumption when you’re looking across the informal settlements, is that it’s poverty, and the realization when that happened – when I realized how much people were paying, I realized it wasn’t poverty, it’s actually structural. And then I started to look at the structural issues around it. Why was it so expensive? Why are people paying so much? And that was when I realized that informality, and it’s really interesting, because it’s just becoming a topic right now in terms of Capitec’s Gerrie Fourie, putting it out there in terms of the employment figures, about what the unemployment rate is. Do we take the informal sector for unemployment? Because what I realized was that the financial system is important – we need to decolonize the financial system, because the reality is, it’s been designed and developed in the first world, and all the rules and regulations, products and processes are all designed in the first world and do not meet the needs of the developing world because they don’t address informality.
Across Africa, more than 85% of income is informal. And in housing, we have one product. If you want to buy a house, you have access to one product. Nobody debates it. Nobody talks about it. We don’t even look at it. What’s the product? It’s a mortgage. If you want to buy a house, you take a mortgage. That’s what you do! And to get a mortgage, you have to have proof of income. You have to have complete formality of everything, which means that before we start 85% of the market across Africa is excluded from housing finance, and that was when it was like, okay, well, how do we address that? How do we begin to address that?
Somebody mentioned to me, they said, you know, you should have a look at blockchain. And I’d had a look earlier at Bitcoin, and I’d sort of looked at it as a technology, and I looked at Bitcoin, not at blockchain, and I looked at Bitcoin, and I went, it’s not useful in this environment. In this context, it’s too volatile, etc, etc. But as I started to explore in more detail the blockchain aspect, the underlying technology of Bitcoin, and I started to understand the aspect of community, how decentralization supports community, I started to realize the potential of blockchain for financial transformation, and that was when I started to get excited, and that was my aha moment, because I realized that we have to have alternatives to the existing systems that we can address these challenges in ways that meet the needs on both sides. We need to meet the needs of capital, obviously, because we need to provide returns, but we also need to meet the needs of the consumers on the ground and those informal consumers, those informal families, the people who are earning variably, intermittently. And how do we address financial products for them, particularly in the housing space, and hence, Empowa was born.
The housing crisis in Africa is staggering—only 16% of urban households have permanent roofs, mortgage rates can exceed 30% in countries like Zambia and Mozambique (a nation of 30+ million people has about 600 mortgages). When you first looked at these numbers, was there a particular statistic or reality that hit you hardest? What made you believe blockchain technology could address what traditional finance couldn’t?
Yeah, I think the issue around it is actually the madness. It feels mad, actually, when we look at these numbers; if you look at the developed world, and you look at how many people earn informally, and you look at the proportion of mortgage to GDP. In the developed world, the numbers of people who earn informally is small compared to the overall population – it’s tiny. The ratio of mortgages to GDP is literally between 60% and 80% in the developed world, and in Africa, the total reverse is true. So the vast majority of people, 85% are earning informally, and the percentage of mortgage to GDP in some countries is less than half a percent. South Africa skews the continent, actually, if you look at the stats, because of South Africa’s relatively sophisticated financial system and portion of the market that is formalized, it addresses that market well, but again, it doesn’t address the informal market. So historically, that’s the white black divide in South Africa. The formal sector is well addressed, is well catered for, but the informal sector is not. But it’s the same across the world, the formal sector is well addressed and its informal sector is not.
You’ve described your team as “a diverse, skilled group frustrated by the status quo and passionate about making a difference.” Can you take us behind the scenes of Empowa’s early days? How did you assemble a team with the right mix of blockchain expertise, housing development knowledge, and connection to African markets?
It was actually really interesting, because Empowa was born during COVID, so everybody was locked down at the time. So everything was done via technology, which is really an interesting process, because it was completely decentralized. So in fact the team was put out and literally started putting together digitally. I was a noob to blockchain, so I started putting it out there on some of the forums – to describe the challenge that we’re looking at, and to ask people what they thought in terms of blockchain, how blockchain could address that. And so literally, the team was born out of people who responded to those questions that I started to put out, and I started to put that out onto blockchain forums and to traditional forums. And literally, people started floating to the top, if that makes sense. And so people who are passionate about the topic, who’ve been looking at the topic, were really frustrated about the current solutions that were there, started looking and started coming up and saying, yeah, we could do this, we could do that, we could put this together.
Hence, the team effectively, literally emerged out of those forums and questions, and groupings. So it was a diverse group of some with Blockchain experience, some with housing experience, some with housing finance experience, all frustrated by the status quo; all understanding that the current systems were not fit for purpose. They did not meet the needs of the people, and something had to change. And one of our team members was actually a founder of an affordable housing company, and was so frustrated because nobody seemed to understand that the off-take finance was the issue, not the construction… Because everybody looks at it and goes: they know the suppliers of affordable housing across Africa… Of course, they’re not buying because if there’s no people to buy it, there are no people to buy it! The only way you can buy it is with cash or a mortgage, and as defined, 85% are immediately excluded; or you buy cash, and there aren’t many people in the developed world who can buy their houses cash… There’s a minuscule proportion.
So the point around it is: how are you going to get developers if you can’t get people to buy the product, and you can’t get people to buy the product because the financial product doesn’t fit. That blockage is the biggest blockage to affordable housing in Africa, and affordable housing is one of the biggest issues across the world right now, not just in Africa.
Most Web3 founders run to Ethereum or Solana. But you went with Cardano. Cardano doesn’t always get the loudest headlines, but you clearly saw something in its DNA. Was it the energy efficiency? The long-term focus? The African partnerships? Help our readers understand why Cardano made sense for Empowa’s mission — especially in the Real-World Assets (RWA) space. Was that a no-brainer, or did you weigh other chains?
We did weigh other chains. But to your point, one of the big issues around housing, obviously, is climate impact, both from a point of view of construction and the impact of the construction. Housing is a huge contributor to carbon emissions; it is one of the one of the more significant contributors to that, so both the construction and usage in terms of heating, cooling, and living conditions.
So the point around that was, if we were going to transform the financial system, we couldn’t just replicate what we’ve done in the rest of the world and try and build the 50 million homes that are required in Africa the same way that we built them historically, because the impact on the environment would be drastic. So we had to look at environmental issues from a housing perspective. That meant we couldn’t be, from a blockchain perspective, blind to the impact on the environment. At that time, Cardano was one of the few proof-of-stake blockchains, compared to Bitcoin, etc, which was proof-of-work, and Ethereum at that time was proof-of-work.
So from our point of view, from a philosophical perspective, proof of stake had to be the kind of blockchain we were looking at because of the environmental impact, and we were also attracted to Cardano because of the academic rigour. We realized that it was not just a blockchain application; this had to integrate into the real world.
People don’t pay their mortgage or their rent with a cryptocurrency; they pay it with real fiat… Therefore, we were going to have to integrate into traditional financial systems, and therefore, we needed the academic rigor of that. We needed to be able to ensure that things were compliant, that there wasn’t an opportunity for anything to go wrong. We really enjoyed the academic rigor that Cardano applied to the project.
The third aspect was their focus at that time; Cardano was specifically focused on Africa. I think at the time, Cardano kind of realized that the blockchain was going to (well, thought at that time, probably more so than has actually happened in reality – that, like mobile money, emerged where it was most needed. It didn’t emerge in the developed world. It emerged in the developing world. I think people assumed, or the Cardano community, particularly at that time, assumed the blockchain would address the needs of the developing world far more effectively because the infrastructure wasn’t there.
So there were a number of projects that were very African-focused, I think, with the crypto winter that emerged quite soon after we started that shifted into things that were more speculative and less actually real-world focused. I think that’s changing again now. I think that pendulum is swinging back, as you say, to real-world assets, tokenization of real-world assets, etc. That sort of mental shift is happening again, and the other blockchains have evolved. Cardano has evolved as well – you know? There’s been a lot of evolution in the space since that time, but I think those were the three major reasons that we chose Cardano at the time.
Real-world assets (RWAs) have become a big narrative in crypto — every protocol is yelling “RWAs” right now, but few are doing it with actual utility. You’re bridging impact and investment… Talk to us about what makes Empowa’s model unique, and how investors are responding when they see actual homes being built.
So yeah, as you say, I think that the real, the really interesting part around what we’re doing is that, effectively, we’re taking traditional concepts and reworking them into methods and methodologies that work in the real world, but are just using the technology as a baseline, if you like. So we’re working on the technology in three basic ways.
The first is through payment. So as outlined, people pay their rent and their mortgages – they pay it in fiat. But the point around that is that if you’re buying a house or you’re paying intermittently and variably, we are recording those transactions on the blockchain so that they are immutable and indisputable. From the point of view of – nobody can touch anything in terms of the ownership of that asset, for the individual, or the family, and that also provides us with a baseline for the investment case, which is the important part of the process, because none of this is going to work, unless this is credible. So the first stage was around payments, recordal, and validation of payments.
Also in Africa, one of the big challenges is that, for banking, if the banks don’t provide mortgages, which, as outlined, they’re not, we’re constantly trying to incentivize the banks to get involved in this market. The reality is, they’re not really inclined to do so. Why? From a business perspective, it doesn’t really make sense, because they’re making enough money; they’re highly profitable, and a lot of the time, they invest their funds into government bonds. Governments across Africa suck up a lot of liquidity in the market. So if I’ve got the choice between investing into a government as a bank – put my money into government bonds, which are secure and provide me with very good returns, or into housing finance for the informal market, which looks to me as extremely risky, I don’t have the systems and processes to put it in place; it means I need to invest in that. I need whole new systems and processes… I don’t understand the market… I don’t have the data on which to make decisions, and it increases my risk… So from a legislative perspective, I’m challenged by all the rules and regulations that I have to comply with… So there’s no incentive for the banks to get involved in this space… So the issue around that is how can we distribute capital? We need alternative mechanisms to distribute the capital.
Our mechanism is that we actually don’t provide funding to the end consumers; we provide funding to the developers for the off-take – that’s the model. So on that basis, we need to validate their transactions to the developers, as well as the repayments, and get visibility to that without the need for audited financial statements. So we’re looking at immediate information on cash flows, which is the key to unlocking this investment market.
So the second part of that is, if you look in the traditional market, what happens is a bank issues a mortgage, it then packages those mortgages up and sells them on to investors. What we’re doing is we’re saying, we can bypass that process by digitizing that investment, enabling investment directly into that off-take finance, and providing a mechanism for that return to be recorded and priced. So that’s the second phase of what we’re doing, and that’s what we’re doing in Kenya with the Nairobi Securities Exchange; that’s what we’re working on with them.
The third stage of what we’re looking at the blockchain for, which is interesting, and we’re not there yet, but we are working actively on it, is the use of stablecoins. Because the issue around this is, if we’re really going to address the backlog of housing in Africa, we need to make the investment attractive. The biggest challenge that we’ve got is that there’s a massive shortage of capital in the African markets, so we need to be attractive to international markets. The challenge with that is that we have currency risk issues, and currency risk issues prevent long-term financing of projects in Africa, to a large extent. So is there a mechanism that we can utilize for new technologies to address this currency? We’re working on that at the moment, to separate our currency from liquidity, and to be able to separate those two risks out in a way that makes the pricing more effective and can reduce the risk as well as provide greater returns for international investors and hard currency investors. And that’s when it becomes really interesting in terms of this demand for finance and the potential for returns, because if somebody is paying between four and seven times more per square meter in an informal settlement, as you can imagine, there’s a significant arbitrage opportunity in that…
You launched Founding Community NFTs for your relatively small but growing community, and they sold out. What’s the vision here? How exactly does this empower your early adopters? How would you explain this to someone who’s not familiar with the Web3 ecosystem?
That enabled us to actually get going. Those founding communities were members of our community; they enabled us to actually get going and to launch the process. So our community is key in terms of what we do. They have been key in our whole process.
Our founding community was actively involved in helping Empowa be established, and also in providing the funding for the proof of concept in Mozambique, because when we looked to traditional funders for the housing finance, we couldn’t find anybody who was prepared to do that, but our founding community did so.
At that time, we were looking at reducing the cost of capital, and we thought, oh, maybe we could do something really interesting and create an art piece that provided you with a financial and impact return. So it was a piece of art that you could buy, but that would also give you a return. What we learned through that process is that as soon as you put a financial return on anything, nobody’s interested in the artwork – it was a very interesting lesson, but the realization was it had to be financial.
Then obviously the legislation started to become murky around – is this a financial instrument? And obviously, we didn’t wanna fall foul of that market, so we stopped that process at that time. Now, as clarification is emerging in terms of the legislative environment, we may be revisiting it… But right now, we’ve stopped the process of the sale of direct NFTs.
What we do utilize our community for is the provision of collateral, and that provision of collateral is a mechanism by which we de-risk the loan, and de-risk the capital investor, and in that process, we utilize the community. It’s quite complex, but it works really well in terms of providing the first-loss de-risking mechanism for investors.
Let’s talk challenges. What’s been the hardest part of building a project like Empowa — both on the ground and on-chain?
How long have you got? *laughs*
The biggest challenge in financial innovation is risk. Nobody wants to actually take risk. So the point around it is when innovating – when presenting innovation, everybody’s looking for where it’s worked before or data. And the point around this is that the data hasn’t existed, and the reason mortgages are the only financial product is because there’s data that exists for a hundred years from other markets or even across Africa. Data exists on the market, so people know how to do it, how to measure the risk, and how to price it. The fact that it’s not working should give us an indication that something’s wrong and that we need an innovation, but yet who can we go to, to invest into this innovation?
That’s been our greatest challenge because at the crypto level, people look for “Wen Moon”, you know? People wanting super returns. That’s not what we are seeking to do. We are seeking to provide consistent returns over a long-term basis. So it doesn’t really fit the crypto kind of community who are looking for good returns quickly. And yet, if we speak to the traditional markets, particularly when we started, it’s changing now, but when we started, blockchain was a place of money launderers and drug dealers, so they weren’t really open to looking at that kind of technology. So it’s really about trying to get the balance, and where our biggest challenges come is innovation – the merging of traditional finance with emerging technologies.
When you look at the environmental impact of construction in Africa over the coming decades, the numbers are staggering—potentially contributing more than 50% of global CO2 emissions if traditional methods are used. How is Empowa addressing this through climate-smart housing, and what technologies are you most excited about?
So the biggest incentive, to be honest, the consumer doesn’t really mind. The consumer’s more concerned around his immediate home than he is around the environment. So he’s more concerned around short-term conditions than he is around the long-term impact and environment of their home.
That change, as we know, takes time. Changing people’s mindsets is a huge challenge; it takes time, and as we know – as we’re currently experiencing-there are setbacks on that road anyway. So the mechanism that we’re utilizing is to incentivize the developers, and obviously that’s through the provision of such financing for their offtake. So if it’s in their business interests to go green and to lessen the impact, then it’s in the interest of not just the world, but in their interest as well. So it’s around trying to take something that is of interest to the world and making it of interest to the business – that’s what we’ve been doing.
So part of that is – we’ve been looking at circular building. We built the first hemp homes in Mozambique, which were highly successful. We built timber homes in Mozambique, which were not so successful. When I say “we”, it’s the local developers that develop these, but we support them with the financing in order to test these technologies, and that’s the process of it. It’s around supporting these innovations in such a way that we can drive those behaviors without trying to influence the consumer, but actually to try and influence the developer, who’s the more important part, and if we make it in the interest of the developer, then they will start to do this, and build to standards such as the EDGE standard, which is the World Bank Green Building standard and all of the funding, etcetera, that becomes available is a requirement. Again, the blockchain is really useful in terms of reporting back on that and verifying that kind of data.
The UN Sustainable Development Goals feature prominently in Empowa’s vision—you’re targeting 14 of the 17 SDGs. With so many potential impact areas, how do you prioritize which to tackle first? And how do you measure success beyond financial returns?
Yeah… Great question!
So the issue really around the SDGs is we address all of them almost by just doing what we’re doing. It’s not even a focus, if you like, it’s just by doing what we’re doing, we are addressing the SDGs. The biggest one is Sustainable Cities; actually, that’s the biggest one that we address, and we address that directly.
Sustainable Cities is the one that, just by this financing, making it available for climate-resilient homes, for individuals, we address that SDG directly. The other ones around gender equality, etcetera – again, we utilize incentives to promote that, and we’ve got to use the blockchain technologies to measure all of these things. So that is really where it becomes useful for the validation of the impact investor. What we tend to find is that a lot of impact investors have their own “pet cause”. So, for example, some will be environmentally focused, some will be gender focused, and others will be financial inclusion focused. So really it’s just around reporting the data to those investors in a way that meets their needs, but the requirements and the processes for us just continue because we are just doing what is the right thing to do in any event, which is: financial inclusion is the right thing to do, gender equality is the right thing to do, environmental sustainability, it’s the right thing to do.
So just by doing the right things, what we have to do is just make sure that we report on that so that it becomes our value to both the investor and to the end user.
Looking forward — what’s next for Empowa? What should we keep our eyes on? Give us a glimpse into the roadmap. More homes? New markets? Token upgrades? What’s the big unlock you’re chasing in 2025 and beyond?
So for us, it’s scaling! Right now, we’ve proven the concept. We’ve proven that it works. It’s now around scaling. We’re in eight countries across Africa. We are in three major markets, which are Mozambique, Kenya, and Nigeria. Those will be scaling this year.
Soon, we’ll be announcing our first collaboration with a traditional financial institution, which is very exciting for us, in terms of putting the technology in place for them and being able to support the process in terms of the funding of affordable houses for the informal sector.
The biggest issue for us is that we have a backlog of 50 million homes across Africa. That’s what we’ve got right now; within the next 10 years, that is gonna more than double. So the point around it is that even if we get 1 million homes, which is our personal mission, which is to support 1 million homes, that is not even going to be effective; at the end of the day, it’s gonna be less than 1% of the market. So the point around us is that’s what we have to do because we have to drive this. Nobody should be living in a tin can! Particularly when they pay a lot of money to do so. That’s the biggest issue. There’s no reason that they have to do that because it’s not poverty, it’s structural. So how can we address their needs and if we can address their needs and address the needs of investors? We can address this problem in a practical, sustainable, and scalable way.
If Empowa succeeds in its mission to enable one million African families to own climate-smart homes, what else will have changed in the African property landscape? What broader shifts in wealth creation and financial inclusion might we see?
It’s massive. The implications of that are massive!
Right now, everybody who pays rent is creating wealth for somebody else. Those brilliant homeowners, instead of an expense, turn that living expense into a wealth creation exercise… So those homeowners are getting access to secure housing, they’re getting access to power, to water, to education. That’s why if you look at the SDGs, that’s why we say we address 14 of the 17, even just by doing what we’re doing. So the implications are so huge. Even if you take one family, being able to move into a home, which is not a tin can, which enables the children to study better. You look at the implications of that for the children going forward, for that family going forward. These are the kinds of things that are immeasurable but massive, and what our continent is so badly in need of.
Yeah, I think that’s a very interesting way of putting it because I’m thinking about sort of the concept of a positive externality, right? Where, when you introduce educational funding into a community that was not literate in the past. The sort of bandwagon effect of that is massive. It’s immeasurable, like you said…
As we move on, for the “budding entrepreneur Renaissance Kids” reading this who are passionate about both blockchain and social impact, what advice would you give them about entering this intersection of technology and real-world problem-solving?
Look at a real-world problem, look at the problem and see how technology might solve that problem, not the other way around. A lot of the new technologies tend to go, “Oh, this is good, and let’s try and find a problem that this addresses.” I would suggest – my recommendation and my advice is to turn that around.
Where’s the problem? What’s the challenge? And how can the new technologies address that problem? Because that’s where the really exciting opportunities lie; because where there’s a problem, there’s an opportunity, and where there’s an opportunity, there’s real potential for transformation and growth.
And you know, one of the things around housing – just talking about those externalities. The World Bank estimates that for every house, five jobs are created. And then if you take that and you say, but beyond that, all the other things around that. So, for example, we found when putting backyard developments into townships in South Africa, the small business that it creates in terms of issues that require the expertise of metal workers who then create burglar bars and gates for those houses, and, and, and…
The impact of that is massive! So, the point around it is what are the challenges? How can we address them? And how can we utilize technology to do that? And that’s where the really exciting opportunities lie.
We’ll wrap it here. This was special. There’s just so much to unpack. My key takeaway from exploring your journey is that Empowa isn’t just building houses — it’s building a new foundation for how capital, community, and crypto can come together; one block at a time. Thank you once again for sharing the Empowa story with us and taking us through your journey, Glen.
Empowa is flipping the script. They’re not waiting for governments… Not building for VC hype…
They’re delivering homes for people who’ve long been priced out of dignity, and that’s timely.